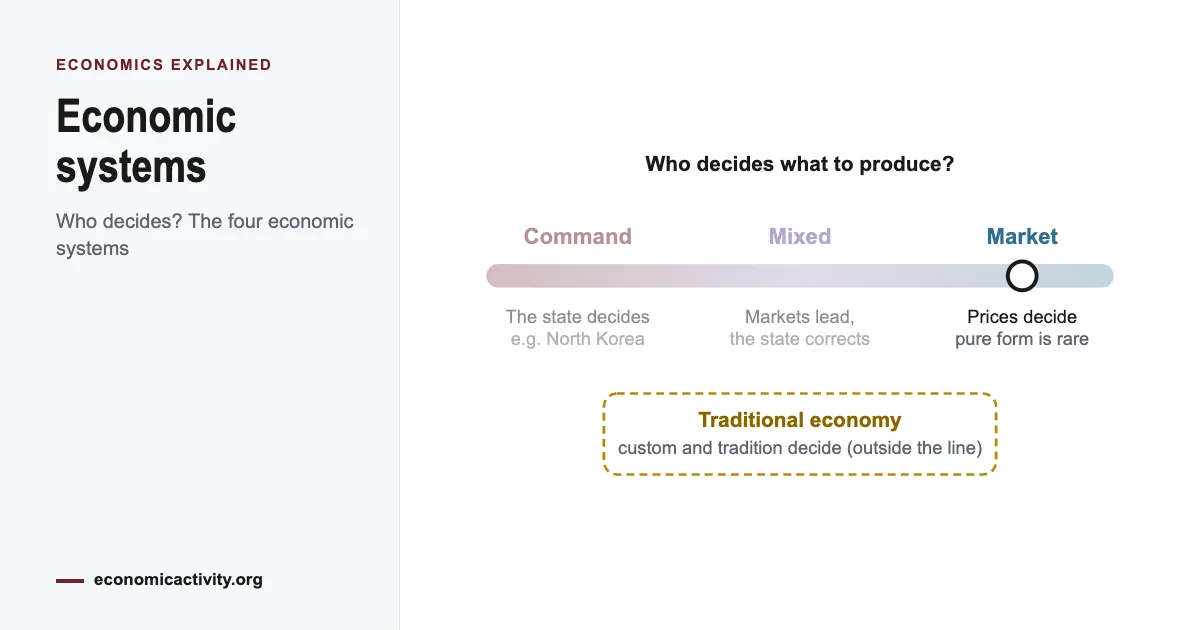
Key Economic Concept: Economic systems organize the production and allocation of resources across four main archetypes: traditional (custom-based), command (state-directed), market (price-driven), and mixed (combining public and private enterprise).
What is an economic system?
An economic system is how a country answers three basic questions: what to produce, how to produce it, and for whom. The answer depends on who owns the means of production and how decisions are made: by custom, by the state, by the market, or by a blend of all three. Economists group these arrangements into four main types.
| System | Who decides | Ownership | Examples |
|---|---|---|---|
| Traditional | Custom and habit | Communal / subsistence | Rural and Indigenous communities |
| Command | Central government | State-owned | North Korea, Cuba |
| Market | Prices, supply and demand | Private | Singapore, Switzerland |
| Mixed | Markets plus government | Private and public | United States, France, most nations |
The four types of economic system
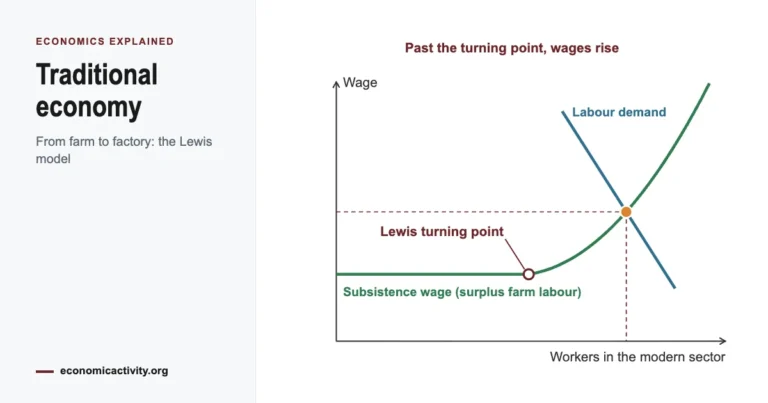
Traditional economy. The oldest system, based on custom, subsistence farming, herding and barter. Roles pass down through generations, and there is little surplus or growth.
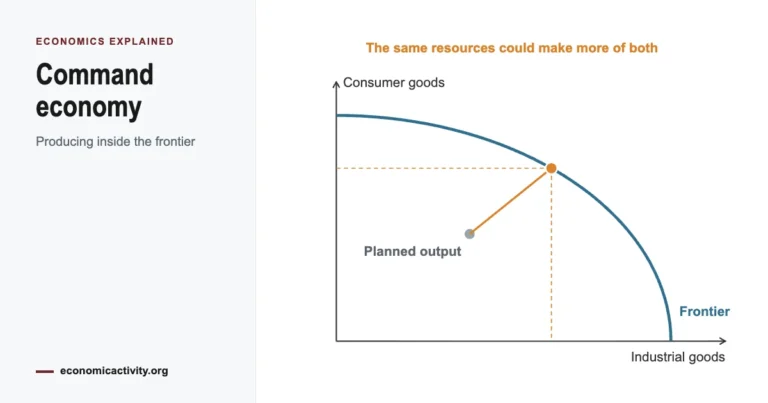
Command economy. The state owns the means of production and a central authority sets output, prices and distribution. It can mobilise resources quickly but tends to cause shortages without price signals.
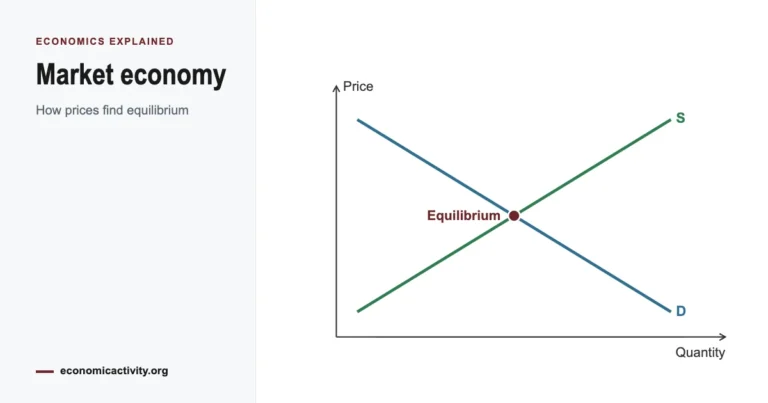
Market economy. Private individuals and firms own resources, and prices set by supply and demand decide what gets produced. Competition and the profit motive drive efficiency and innovation, but can widen inequality.
Mixed economy. The most common system today. Private markets lead, while the government regulates, provides public services and redistributes income. Countries differ only in how large the state’s role is.
Which system do countries actually use?
In practice, almost every modern country is a mixed economy. The debate is only about where it sits between free markets and state control. Pure command economies are rare (North Korea is the clearest), and pure market or traditional economies barely exist. The system a country chooses shapes every economic activity within it, from how markets are organised to how wealth is shared. You can see how this plays out country by country in our economic-system profiles, such as Mexico’s economy.
Key takeaways
- An economic system decides what a society produces, how, and for whom.
- The four types are traditional, command, market and mixed.
- They differ in who owns resources and who makes decisions.
- Almost every country today runs a mixed economy.
Prices as signals: how markets coordinate without a planner
Every economic system has to answer the same questions: what to produce, how, and for whom. A planner tries to answer them by gathering information and issuing orders. A market answers them through prices, which work as signals that pass information from person to person without anyone needing to see the whole picture.
Suppose a large tin mine floods. Tin becomes scarcer and its price rises. Users of tin do not need to know why; the higher price alone tells them to economise. Can makers use thinner coatings, electronics firms switch to other metals, recyclers collect more scrap and mine owners reopen marginal mines. Thousands of separate decisions add up to exactly what the situation requires: less tin used and more tin found.
The economist Friedrich Hayek used this very example in 1945 to argue that the knowledge an economy needs is scattered across millions of people, and no central planner can gather it all in time. This is a key reason command economies struggled with shortages and waste. Prices are not perfect signals, though: they ignore costs that nobody pays for, such as pollution, which is one reason most countries end up with mixed economies.
Concept check
What are the four types of economic system?
Which economic system is most common?
How do economic systems relate to capitalism and socialism?
Sources
- Encyclopaedia Britannica, Economic system — retrieved 2026-07-05 — britannica.com
- Heritage Foundation, Index of Economic Freedom — retrieved 2026-07-05 — heritage.org
Last updated: October 2026

Leave a Reply