The factors of production are the four resources an economy uses to make goods and services: land (natural resources), labor (human effort), capital (machines, tools and buildings) and entrepreneurship (organising the other three and taking the risk). Each earns its own return: rent, wages, interest and profit. Some economists now add a fifth factor: knowledge or technology.
Key takeaways
- There are four classic factors of production: land, labor, capital and entrepreneurship. They earn rent, wages, interest and profit.
- The world’s labor force reached about 3.66 billion people in 2023 (World Bank).
- Capital does not mean money; it means the tools, machines and buildings used to produce other goods.
- Services generated 63.3% of world GDP in 2024 (World Bank), evidence of a shift toward a knowledge-based fifth factor.
What are the factors of production?
Every good or service starts from the same four building blocks. In 2023 the global labor force reached roughly 3.66 billion people (World Bank, Labor force total, 2023), and each worker combines with land, capital and entrepreneurship to create output. The factors of production are the scarce inputs that economies turn into the goods and services people consume.
Who owns and combines these inputs? economic agents (households, firms and governments) do, and each factor earns a distinct kind of income. Economists have grouped inputs this way since the classical era, because it explains both how things get made and how the income from making them is shared.
| Factor | What it is | Examples | Income it earns |
|---|---|---|---|
| Land | Natural resources provided by nature | Soil, water, forests, minerals, oil | Rent |
| Labor | Human physical and mental effort | Workers, engineers, teachers, farmers | Wages |
| Capital | Human-made goods used to produce more goods | Machines, tools, factories, equipment | Interest |
| Entrepreneurship | Organises the factors and bears risk | Founders, innovators, business owners | Profit |
Land: the natural-resources factor
Land is far more productive than its small headline share suggests. As of 2022, agricultural land made up 37.0% of the world’s land area (World Bank and FAO, 2022), yet in 2024 agriculture, forestry and fishing produced just 4.1% of world GDP (World Bank, 2024). In economics, land means every natural resource (soil, water, forests, minerals, oil and air), and the income earned from letting others use it is called rent.
Because land is largely fixed in supply, resource-rich countries often build entire industries in the primary sector around it. A small share of GDP does not mean a small role: food, energy and raw materials underpin every other sector.
Labor: the human factor
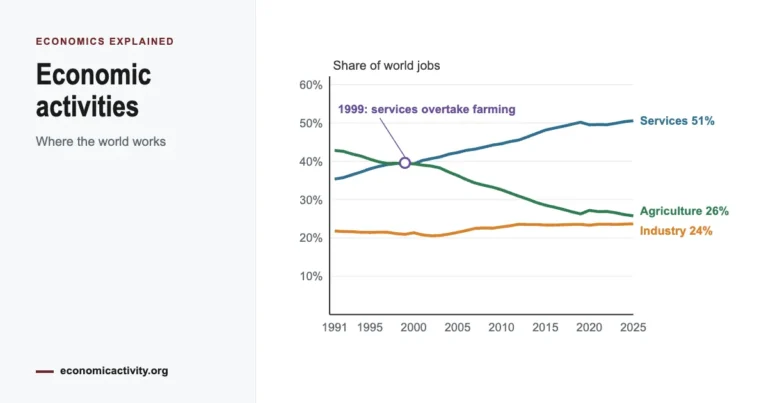
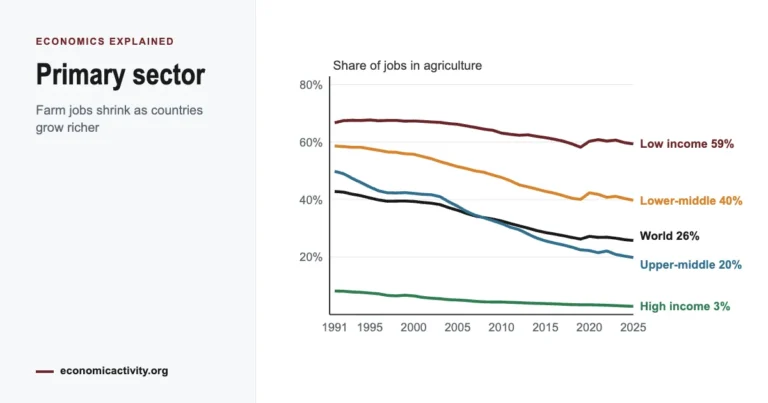
Labor is the effort people put into production, and it is the factor most of us supply. In 2023 services employed 49.9% of the world’s workers, agriculture 26.6% and industry 23.5% (World Bank and ILO modelled estimates, 2023). The payment for labor is wages, and its quality, shaped by education, training and health, is often called human capital.
The interesting part is what happens when you compare where people work with where value is created.
Agriculture takes more than a quarter of the world’s jobs but returns only a twentieth of its output, while services do the opposite. That gap is the story of economic development in one chart: as economies grow, labor and capital move out of low-productivity land-based work and into services and knowledge.
Capital: tools, not cash
In economics, capital means the human-made goods used to produce other goods, not money. In 2024 the world reinvested 26.3% of its GDP as gross capital formation (World Bank, 2024), building the machines, factories, computers and infrastructure that raise output per worker. The return on capital is interest.
Money is better described as financial capital: it is used to buy the real capital goods that do the producing. This distinction trips up a lot of students: a bank balance is not capital until it becomes a machine, a building or a tool.
Entrepreneurship: organising the risk
Entrepreneurship brings the other three factors together, decides what to produce, and accepts the risk of success or failure. Small and medium enterprises, the main vehicle for entrepreneurship, account for about 90% of businesses and more than half of employment worldwide (World Bank, SME Finance). The reward for taking on this risk is profit.
Without the entrepreneur, land, labor and capital sit idle; someone has to combine them and bet that the result is worth more than the parts. That coordinating, risk-bearing role is why many economists treat entrepreneurship as a factor in its own right rather than a type of labor.
Is there a fifth factor of production?
Many economists now argue for a fifth factor: knowledge, technology or information. The evidence sits in the numbers. Services, where most knowledge work lives, produced 63.3% of world GDP in 2024 but only about 49.9% of jobs in 2023 (World Bank, 2024 and 2023), a sign that value increasingly comes from ideas rather than headcount.
This is the world of the quaternary sector: research, software, data and consulting. Whether knowledge is a genuine fifth factor or simply a powerful form of capital and entrepreneurship is still debated, but its weight in modern output is not.
How the factors of production shape an economy
Why do two countries with similar populations produce such different amounts? The answer usually lies in how they combine and grow their factors of production. A country’s economic system decides who directs these resources: in a market economy, prices guide households and firms; in a command economy, the State allocates them.
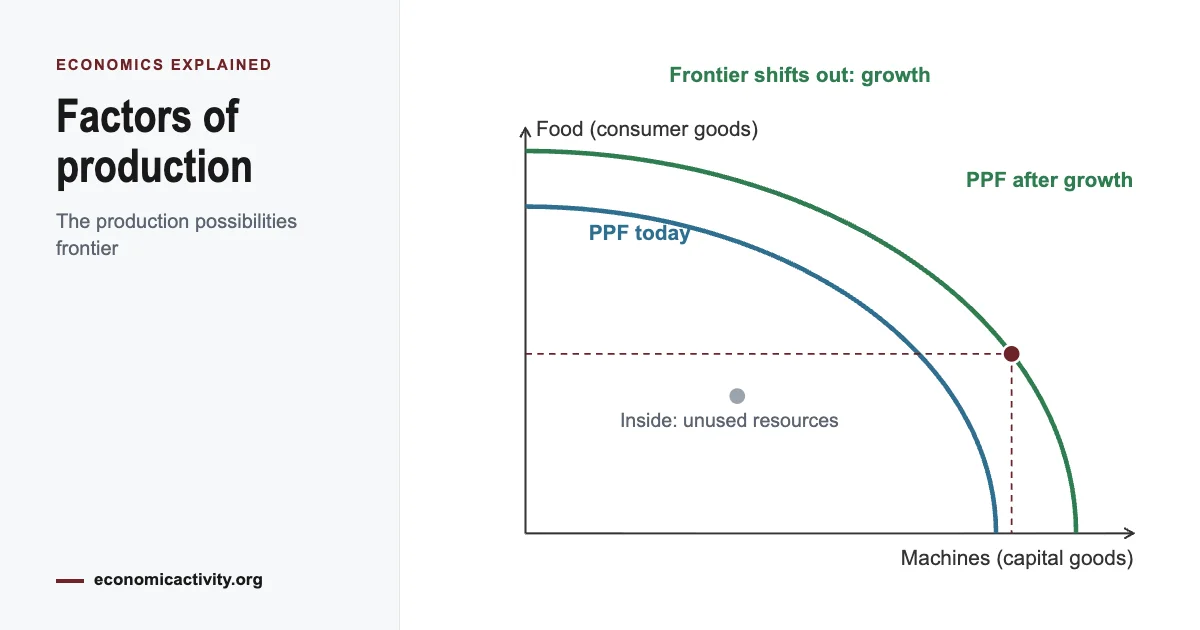
Every activity across the four sectors of the economy (primary, secondary, tertiary and quaternary) is a different recipe made from the same four ingredients. Grow the quantity or quality of any factor, and you expand what the economy can produce.
The cleanest way to see what the factors of production do is the production possibilities frontier (PPF). It draws every combination of two goods that an economy can produce when it uses all of its factors fully and efficiently.
Diminishing returns: why more of one factor helps less and less
The factors of production work best in balance. Add more of one factor while holding the others fixed, and output rises, but each extra unit adds less than the one before. This is the law of diminishing marginal returns. The marginal product is the extra output from one more unit of a factor, such as one more worker.
Picture a farm with a fixed plot of land. The first worker can plant, weed and harvest alone and produces 10 sacks of grain. A second worker adds 9 more. By the sixth or seventh worker, people are getting in each other’s way on the same land, and each newcomer adds only a sack or two. Total output still rises, but more and more slowly.
The idea goes back to the classical economists, who worried that a growing population on a fixed amount of farmland would push food per person down. It appears throughout economics. It is why firms give workers more machines rather than hiring more people, why the cost of producing extra units eventually rises, and why poorer countries with little capital can grow fast by investing while rich countries get less from each extra machine (see emerging markets). The way out is to grow all the factors together, or to improve technology so that the same land, labour and capital produce more.
Concept check
What are the four factors of production?
Is money a factor of production?
What income does each factor of production earn?
Is there a fifth factor of production?
Sources
- World Bank, Labor force total (SL.TLF.TOTL.IN), 2023 — retrieved 2026-07-04 — data.worldbank.org
- World Bank / ILO, Employment by sector (agriculture, industry, services), 2023 — retrieved 2026-07-04 — data.worldbank.org
- World Bank, Value added by sector (% of GDP), 2024 — retrieved 2026-07-04 — data.worldbank.org
- World Bank and FAO, Agricultural land (% of land area), 2022 — retrieved 2026-07-04 — data.worldbank.org
- World Bank, Gross capital formation (% of GDP), 2024 — retrieved 2026-07-04 — data.worldbank.org
- World Bank Group, SME Finance topic page — retrieved 2026-07-04 — worldbank.org
Last updated: August 2026

Leave a Reply